Electronic Components Sales Market Analysis and Forecast (Q3 2026)
Table Of Contents
Prologue
1 Macroeconomy & Semiconductor Trade
1.1 Macroeconomic Review
(1)Global Manufacturing Maintains Moderate Expansion with Stabilizing Divergence
(2)Stable Profitability & Accelerated Exports for Electronic Information Manufacturing
(3)Widening Divergence in End-market Demand with Inventory Fluctuations
1.2 Semiconductor Market Overview
(1)Semiconductor Sales Hit New High, Super Cycle on Upswing
(2)Sharp Growth in Semiconductor Imports & Exports, Trade Keeps Rising
(3)Semiconductor Indexes Rally Together, Hitting Record Highs
1.3 Chip Lead Time & Price Analysis
(1)Lead Time and Price Trend
(2)Supplier Lead Time Summary
1.4 Manufacturer Order & Inventory Analysis
2 Semiconductor Supply Chain
2.1 Upstream Players
(1)Semiconductor Equipment & Silicon Wafers: Rising Volume & Profit
(2)IDM/Fabless Chip Suppliers: Explosive Profit
(3)Foundry: Full Capacity & Full Shipment
(4)OSAT: Stable Revenue with Rising Profit
2.2 Distributors: Soaring Performance
2.3 System Integrators: Improving Profit
2.4 End-Market Vertical Breakdown
(1)Consumer Electronics: Downgraded Expectations
(2)New Energy Vehicles: Falling Profit
(3)Industrial Control: Recovering Demand
(4)Photovoltaic: Persistent Losses
(5)Energy Storage: Revenue Growth with Thin Margins
(6)Data Centers: Sustained High Growth
(7)Communications: Weak Growth
(8)Medical Devices: Divergent Recovery
3 Distribution and Sourcing Opportunities and Risks
3.1 Investment & Sourcing Opportunities
3.2 Downside Risk Factors
4 Concluding Remarks
Disclaimer
Prologue
1 Macroeconomics and Semiconductor Trade
1.1 Macroeconomic Review
(1)Global Manufacturing Maintains Moderate Expansion with Stabilizing Divergence
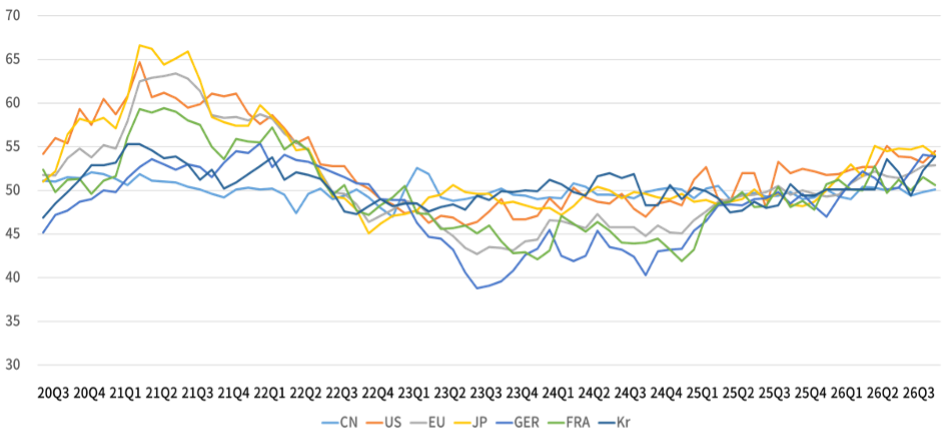
In 2026 Q3, the global manufacturing PMI stayed in moderate expansion amid stabilized internal divergence. China returned above the boom-bust line in September, while the US, Japan and South Korea maintained strong prosperity. The steady backdrop of global manufacturing underpins the growth of semiconductor end-market demand.
Chart 1: Global Major Economies Manufacturing PMI, 2026 Q3
Source: NBSPRC
(2)Stable Profitability & Accelerated Exports for Electronic Information Manufacturing
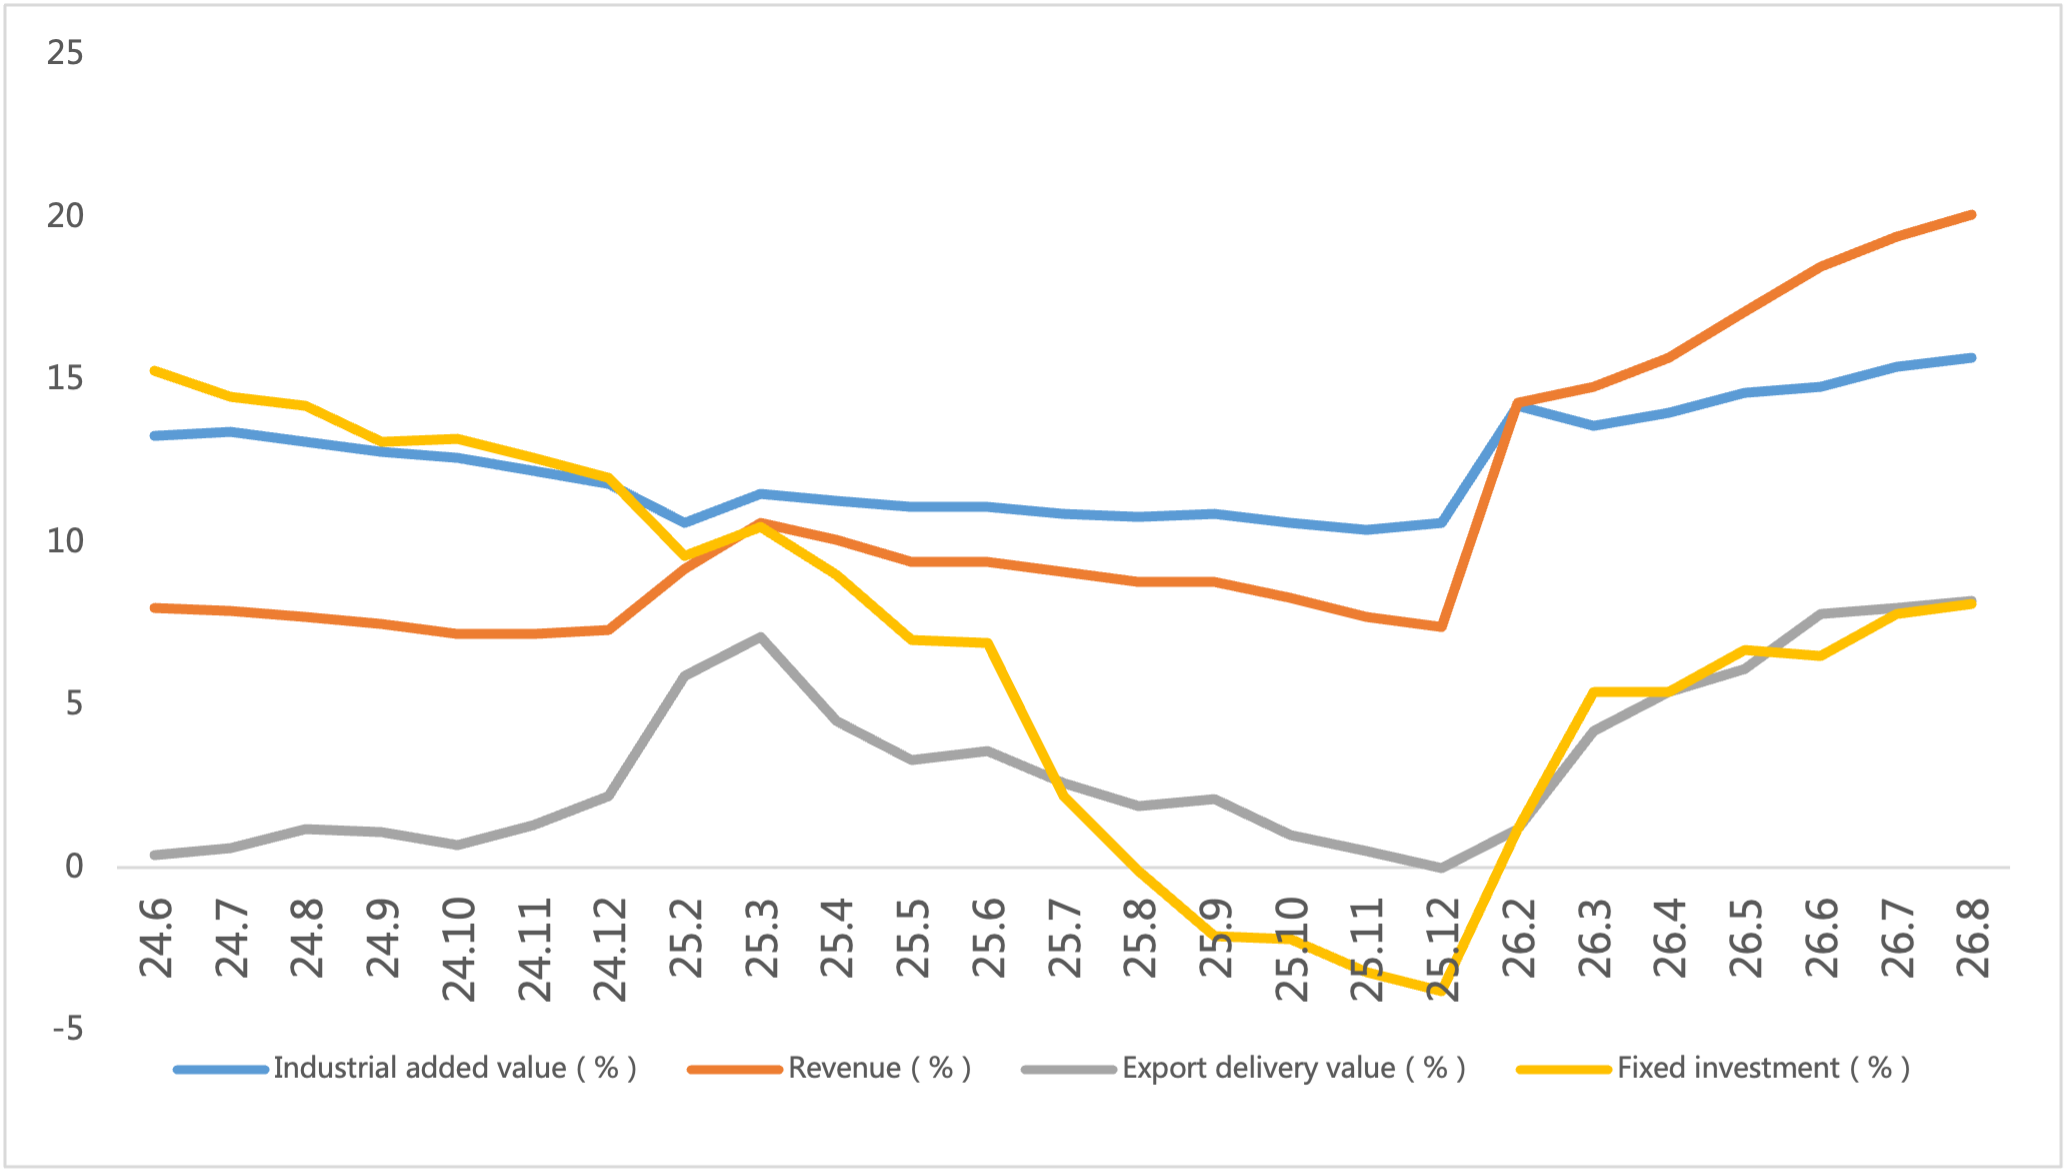
From Jan to Aug 2026, China’s electronic information manufacturing sector achieved rapid production growth with rising exports, solid profit improvement and steady investment growth, showing sound overall industry performance.
Chart 2: Latest Operating Metrics of China’s Electronic Information Manufacturing Industry
Source: MIIT
(3)Widening Divergence in End-market Demand with Inventory Fluctuations
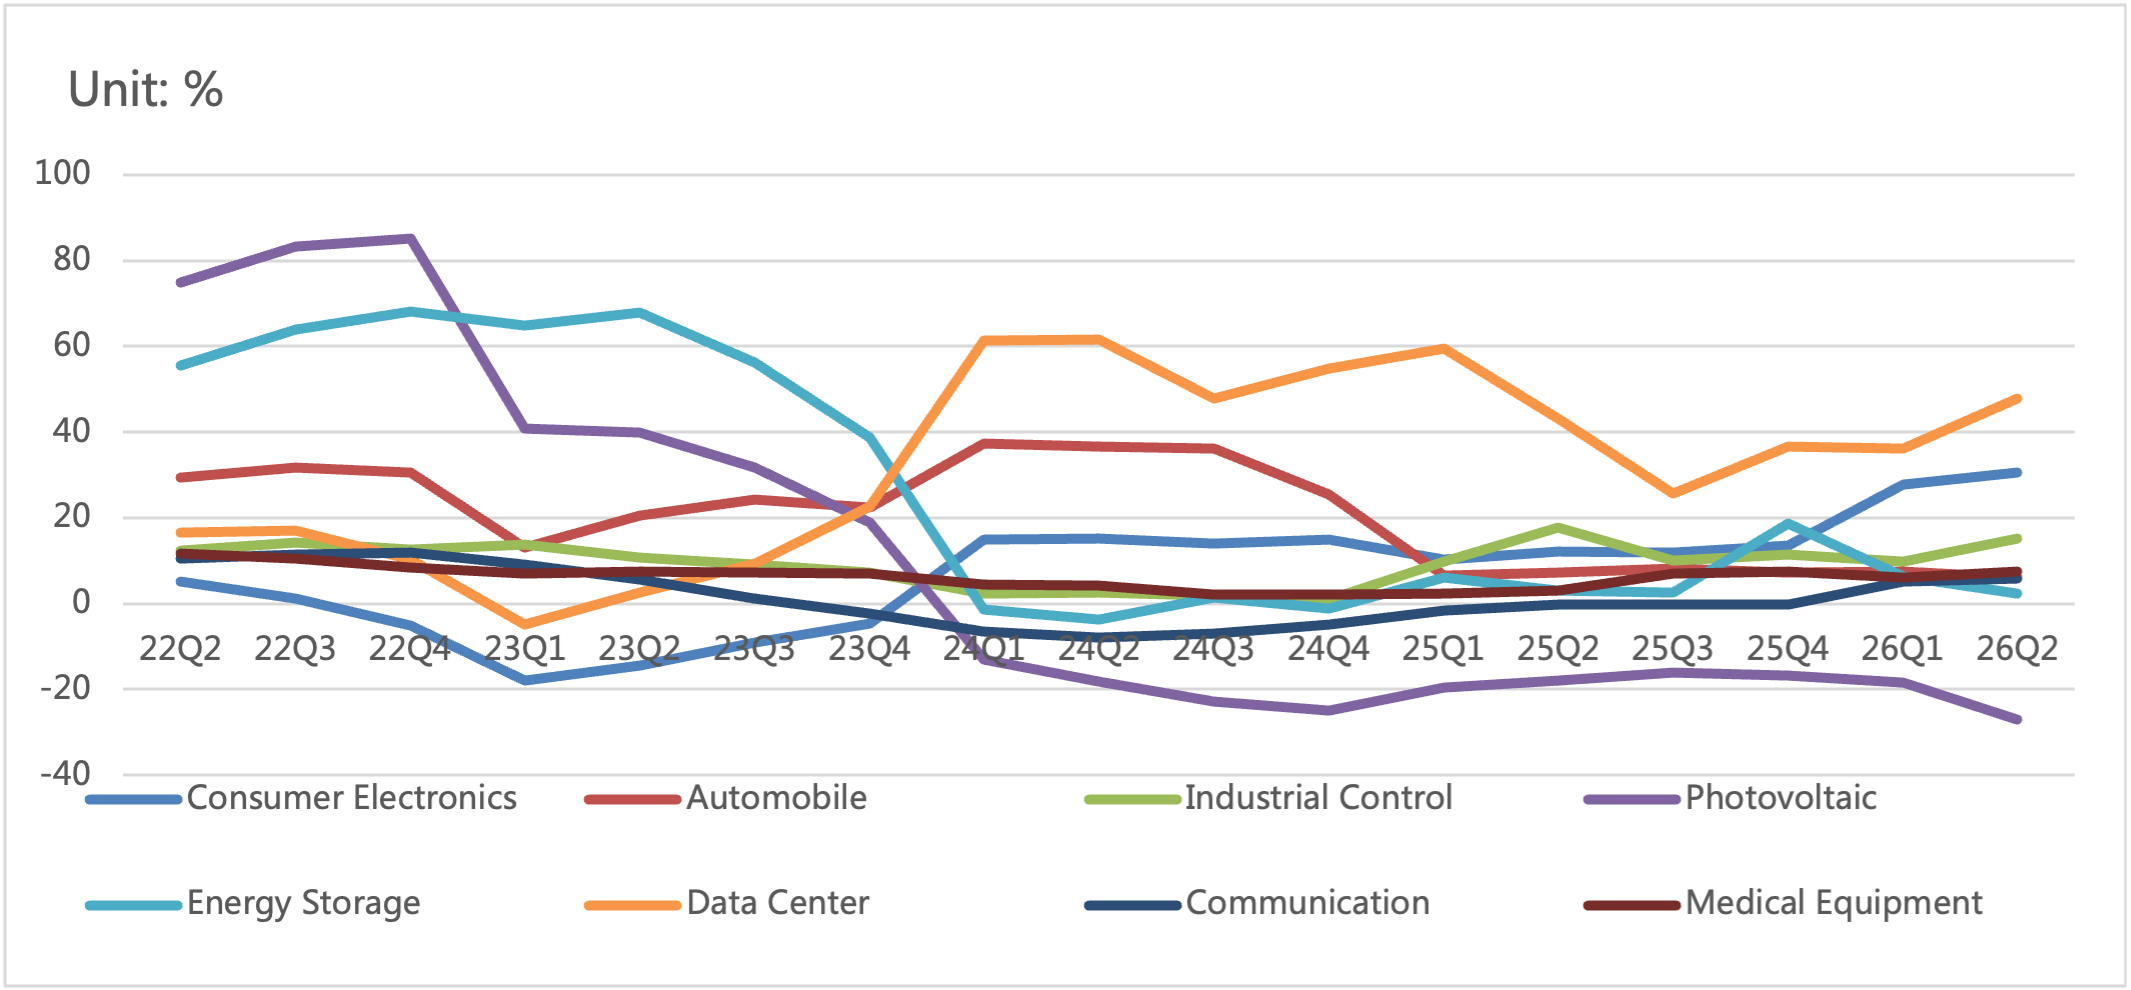
Latest data shows data center revenue and profits continue to lead growth, automotive demand recovers slowly, while the photovoltaic sector remains loss-making.
In terms of revenue growth rate, data centers rank top, consumer electronics stabilize quarter-on-quarter, and communication stays weak.
Chart 3: Average Revenue Growth of End-market Vendors
Source: Chip Insights
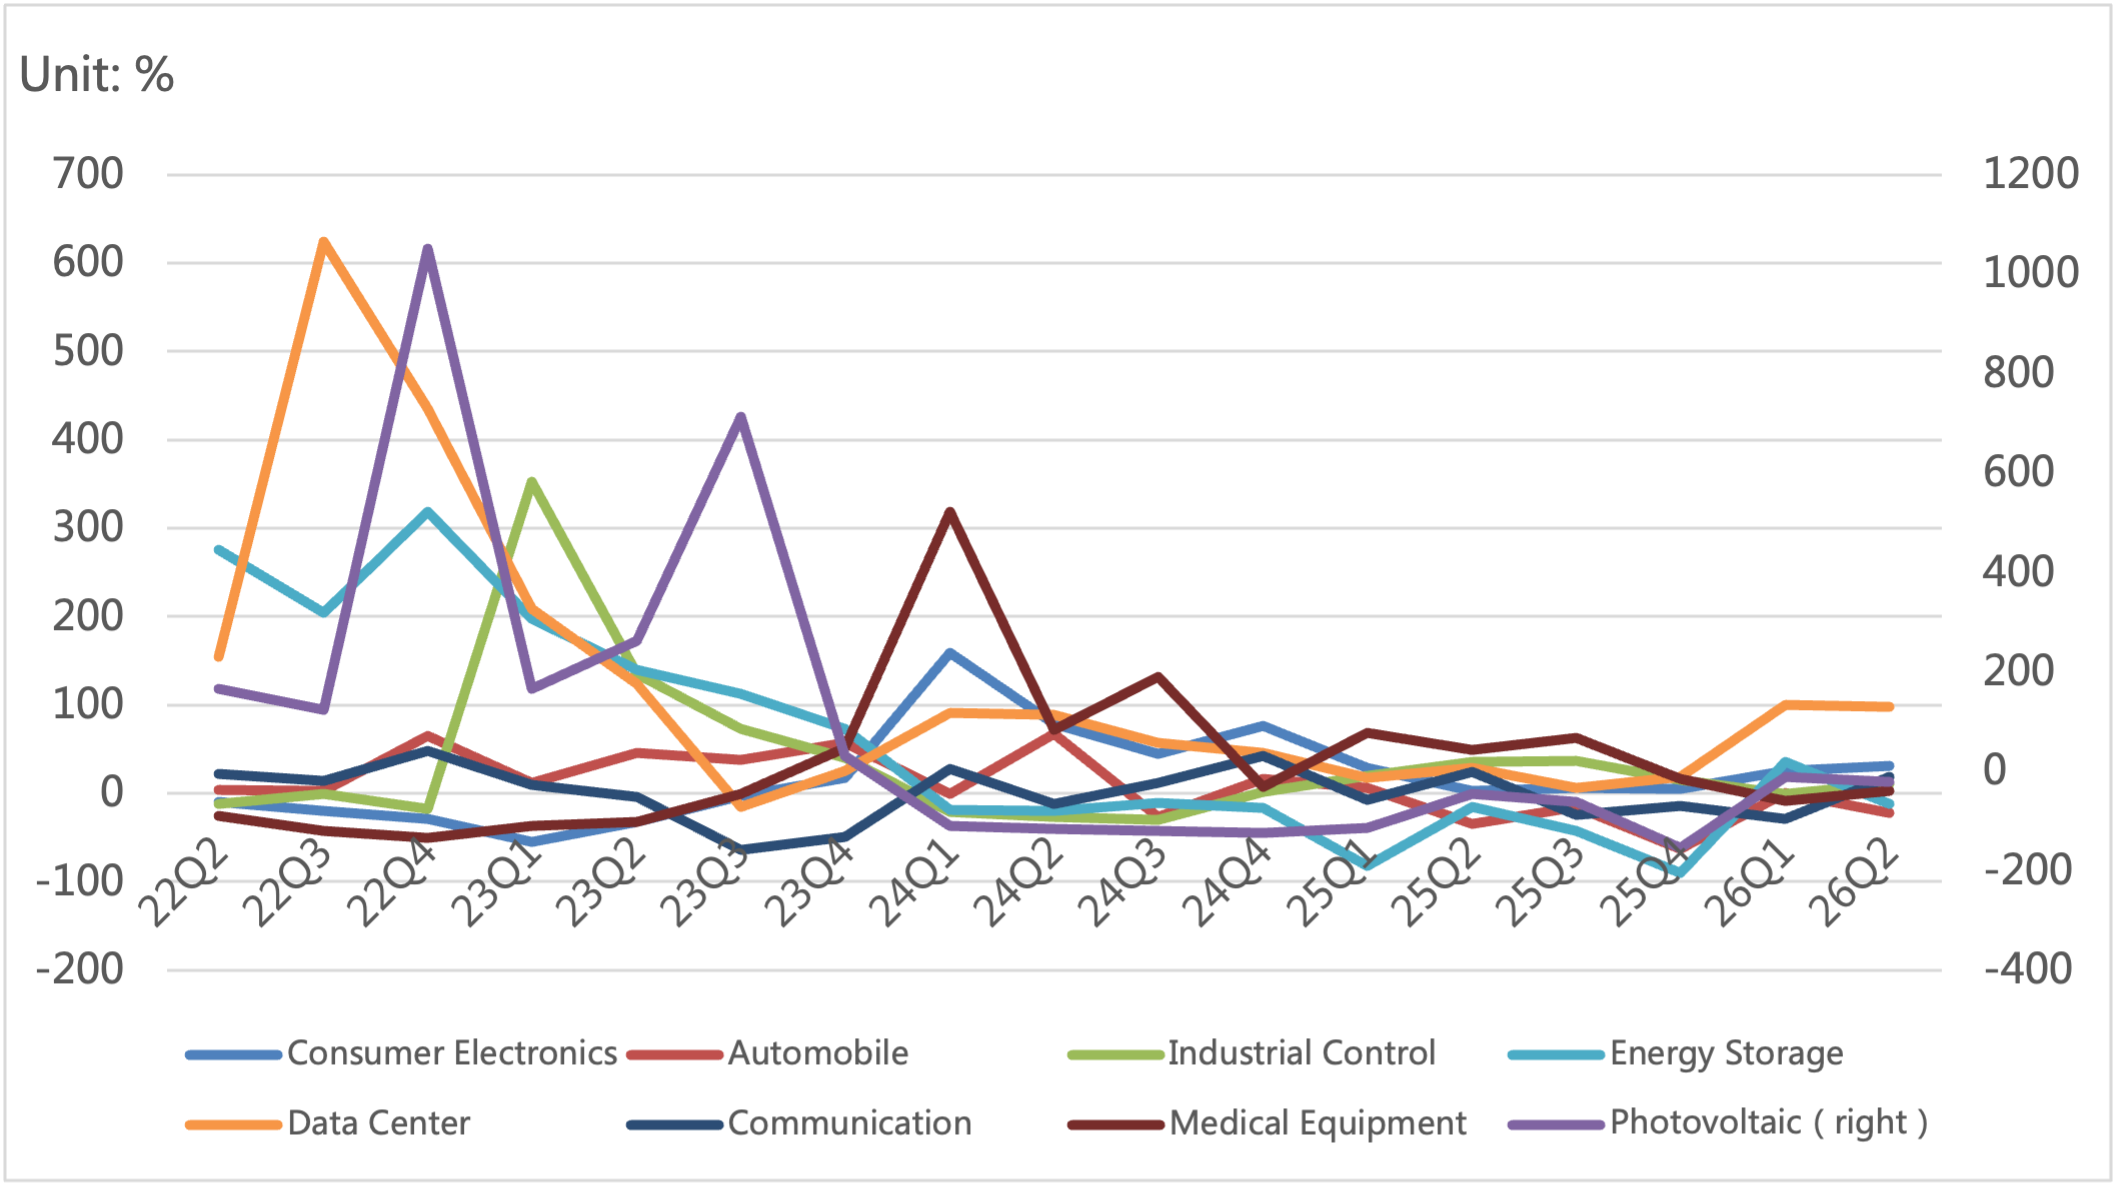
For net profit, energy storage and consumer electronics see marginal recovery.automotive and industrial control remain muted.PV stays under pressure.
Chart 4: Average Net Profit Growth of End-Market Players
Source: Chip Insights
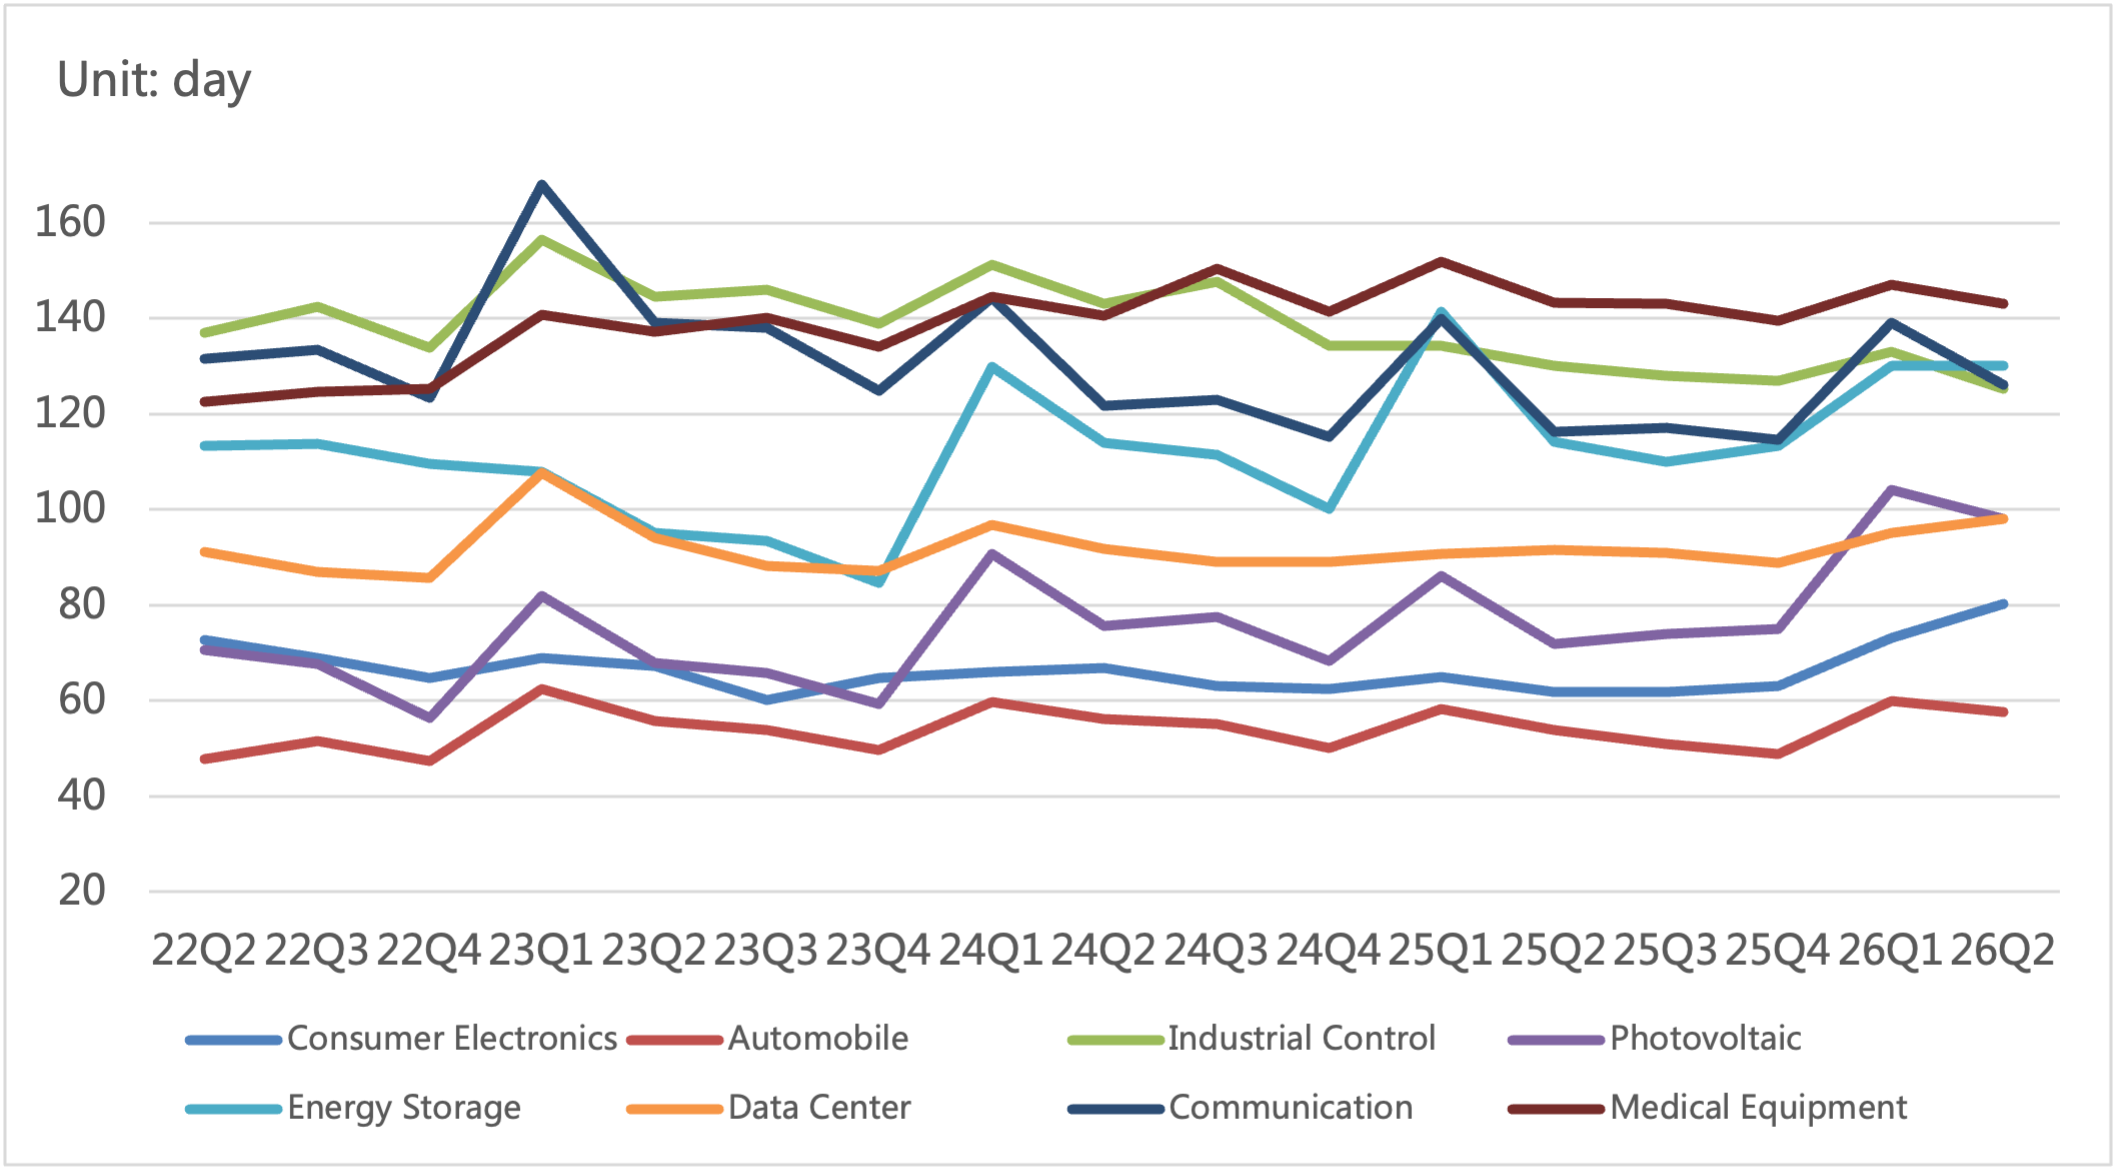
On inventory trends, end markets did not embark on broad active restocking.trends show obvious divergence.
Chart 5: Average Inventory Trend of End-Market Players
Source: Chip Insights
For more information, please refer to the attached report.